Construction finance is vital to any construction project. It can be used to finance new projects, pay suppliers , and to purchase machinery or equipment that will help you work more efficiently on your next big construction project. Construction financing is a type of loan used to finance the construction or remodeling of a home or any other construction. The loan is generally used to pay for the cost of labor and materials, as well as any other expenses that are associated in the process of construction. It can be obtained through many different sources, including banks, credit unions, and private lenders. The terms for construction financing can be very different so it is essential to search around to find the most competitive rate. Construction loans typically have more interest rates than traditional mortgages. Construction loans are a fantastic way to finance the construction or renovation of a house or other type of building.
Before you begin the construction process, it’s important to understand the basics of financing construction. The financing usually comes as the form of a mortgage. A mortgage is a loan that is secured with your property. The mortgage will usually cover the costs of the land as well as the expense of materials and labor for the construction project. In certain instances, the mortgage may also pay for permits as well as other costs associated to the process of construction. After you’ve secured financing you must ensure that your plans are on the right track and keep your spending within your budget. If you follow through, you will be enjoying your new business or home space for many years to come.
Short-term options
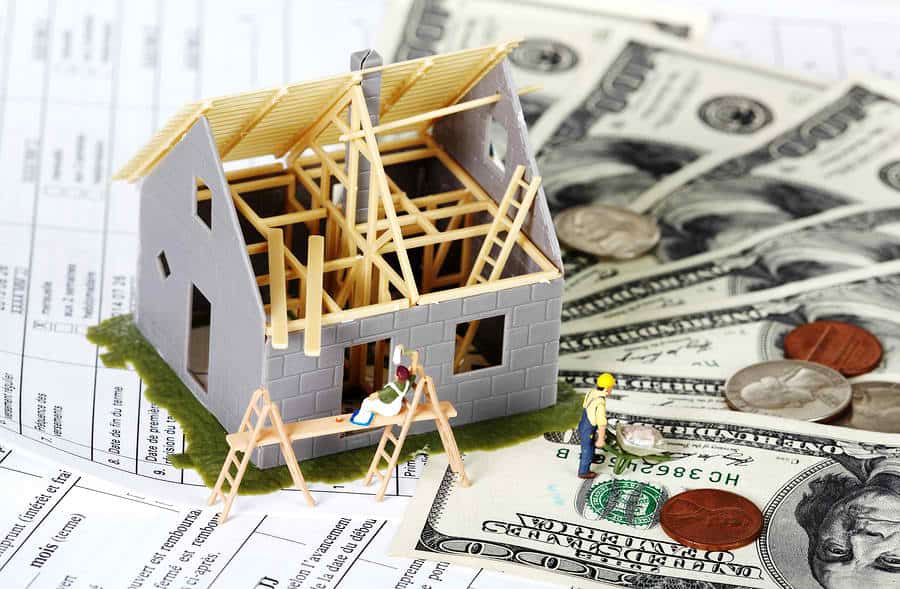
A construction loan might be the best option for you if your need construction financing for a shorter time. A construction loan typically offers you twelve months to complete your project. If you’re sure that your project will be completed within the agreed timeframe, this loan can be an excellent option. However, you’ll have to pay regular loan payments throughout the construction. Once the construction phase is completed it’s time to pay off the remaining of the loan. Construction loans are a good choice for those in need of short-term financing however, they are not suitable people who require longer-term financing.
Convenient
Construction financing can help to make the construction process more convenient by providing an all-in-one source of funding to cover all costs associated with construction. This means you don’t have to make loans with multiple lenders, which can help you save time and cut down on the hassle. Construction financing is also a great way in saving money by providing favorable interest rates and terms. Construction financing gives borrowers the flexibility to choose the repayment timeframe that is most suitable for their requirements. Anyone wanting to buy a house or embark on major construction projects can find construction financing a valuable instrument.
Paying low initial installments
Construction financing is an effective way to secure the funds you need to get your project off the ground. However, one of the biggest difficulties is making the initial payment. There are numerous options available for those in need of financial assistance to cover the initial cost. Consider looking into construction financing with lower beginning payments. This could help you begin the process of completing your project without needing to pay the funds all at once. Another option is to locate an approved construction lender willing to match your budget to design a payment schedule which is flexible for you. This can help you pay the loan more quickly and help avoid financial stress later. Whatever you decide to do building financing can assist you in getting the funds you require for your desired project.
Let us help you build the home of your dreams
If you’re looking to build the home of your dreams, construction financing may assist in making it a reality. With construction financing, you’ll borrow the money you need to finance the expense of construction, making it possible to construct your dream home without the need to dip into savings. The term for construction loans is typically less than conventional mortgages, and you will only be charged interest on the amount that you borrowed during construction. This can reduce your total cost. When the construction is finished then you can turn your construction loan into a mortgage that is permanent. This ensures that you will only need one loan when your home is completed. Speak to your construction financing lender.
For more information, click optimal loan solutions